You are about to enter our website for institutional investors in the UK. If you would like to change website, go back to our homepage.
Last modified: 16 January 2026
Website terms of use
These terms and conditions of use, together with the documents we refer to in it, (“Terms and Conditions”) govern your use of this website which is located at www.rlam.com (“Website”). Use of this Website includes accessing, browsing, or purchasing products or services on it.
Please read these Terms and Conditions carefully before you start to use this Website, as these will apply to your use of this Website. We recommend that you print a copy of these Terms and Conditions for future reference.
By using this Website, you confirm that you accept these Terms and Conditions and that you agree to comply with them.
Other applicable Terms and Conditions
The following additional terms of use also apply to your use of this Website:
- Our Privacy Policy, which sets out the terms on which we process any personal data we collect from you, or that you provide to us. By using this Website, you consent to such processing and you warrant that all data provided by you is accurate.
- Our Cookie Policy, which sets out information about the cookies on this Website.
If you purchase products or service from a company within our group of companies (“Royal London Group”), that purchase may also be subject to terms and conditions applicable to that product or service. If these Terms and Conditions conflict with any product or service-related terms and conditions, then the relevant product or service-related terms and conditions shall prevail.
Information about us
This Website is a site operated by Royal London Asset Management Limited (“Royal London Asset Management Limited”, “we”, “us” or ”our”). We are registered in England and Wales under company number 02244297 and have our registered office at 80 Fenchurch Street, London, EC3M 4BY, United Kingdom. In these Terms and Conditions, references to us apply also to companies in the Royal London Group. Details of the companies that are part of the Royal London Group, including The Royal London Mutual Insurance Society Limited, can be found here.
We are authorised and regulated by the Financial Conduct Authority. Our firm reference number is 141665. You can check this on the Financial Services Register.
The Royal London Group’s registered VAT number is 368 5244 27.
Changes to these Terms and Conditions
We may revise these Terms and Conditions at any time by amending this page. When we post changes to these Terms and Conditions, we will revise the 'Last modified' date at the top of this page.
Please check this page from time to time to take notice of any changes we make, as they are binding on you.
Changes to this Website
We may update this Website from time to time, and may change the content at any time. However, please note that any of the content on this Website may be out of date at any given time, and we are under no obligation to update it.
We do not guarantee that this Website, or any content on it, will be free from errors or omissions.
Accessing this Website
This Website is made available free of charge.
We do not guarantee that this Website, or any content on it, will always be available or be uninterrupted, or that this Website will be secure or free from bugs or viruses. Access to this Website is permitted on a temporary basis. We may suspend, withdraw, discontinue or change all or any part of this Website without notice. We will not be liable to you if for any reason this Website is unavailable at any time or for any period.
You are responsible for making all arrangements necessary for you to have access to this Website.
You are also responsible for ensuring that all persons who access this Website through your internet connection are aware of these Terms and Conditions and other applicable terms and conditions, and that they comply with them.
Use of this Website
This Website is not intended for distribution to, or use by, any person in a country where such distribution, or use, would be contrary to local laws or regulations. You agree to use the Website only for lawful purposes and in a way which does not infringe the rights of anyone else or restrict or inhibit anyone else's use and enjoyment of the Website. Website content must not be copied or reproduced, modified, redistributed, used or otherwise dealt with for any other reason without our express written permission. You are not entitled to use the content of the Website for commercial exploitation in any circumstances.
This Website is made available to, and is provided for, the benefit of persons and corporate entities that meet the criteria listed below only. This Website is not for the use of, or directed at, any person in the United States of America or Hong Kong. It is not made available to, or for the benefit of, US Persons (as defined in US securities laws) in any jurisdiction.
Information on this Website is issued into the European Economic Area by FundRock Distribution S.A. (“FRD”), the EU distributor for Royal London Asset Management Limited. FRD is a public limited company, incorporated under the laws of the Grand Duchy of Luxembourg, with registered office at Airport Center Building, 5, Heienhaff, L-1736 Senningerberg, Luxembourg and registered with the Luxembourg trade and companies register under number B253257 with authorisation of establishment number 07/21 under the law of 5 April 1993, as updated from time to time. FRD is authorised and regulated by the Commission de Surveillance du Secteur Financier (“CSSF”).
For investors in the United Kingdom:
Information on this Website is made available to investors based in the UK except those classified as US Persons.
For investors in Austria, Belgium, Denmark, France, Germany, Ireland, Italy, the Netherlands, Norway, Spain, Sweden and Portugal:
If you are not able to access this Website according to the criteria in this paragraph, or you do not understand if you fulfil the relevant criteria, you must not agree to these Terms and Conditions. This information is made available solely to persons that meet the criteria of “Professional Investor”, or are authorised as a financial intermediary or investment manager by your financial regulator. If you do not meet these criteria, you may not proceed any further and must leave this Website. For the avoidance of doubt, the information contained on this Website is not available to the general public.
By entering this Website, you confirm that you meet the entry criteria described above according to the laws and regulations of your home state country and regulator.
For investors in Canada:
If you are not able to access this Website according to the criteria in this paragraph, or you do not understand if you fulfil the relevant criteria, you must not agree to these Terms and Conditions. This Website is directed at Accredited Investors and Permitted Clients (as defined in Canadian securities laws) in Canada only and is not directed at members of the public. This Website is not, and under no circumstances is to be construed as, an advertisement or a public offering in Canada. No Securities Commission or similar authority in Canada has reviewed, or in any way passed comment, upon this Website or the merits of the content herein, and any representation to the contrary is an offence.
By entering this Website, you confirm that you meet the entry criteria described above according to the laws and regulations of Canada.
For investors in Singapore:
If you are not able to access this Website according to the criteria in this paragraph, or you do not understand if you fulfil the relevant criteria, you must not agree to these Terms and Conditions. This Website is provided exclusively for the use and information of Institutional Investors (as defined in the Securities and Futures Act (Singapore Statute Cap. 289)) in Singapore only.
By entering this Website, you confirm that you meet the entry criteria described above according to the laws and regulations of Singapore.
For investors in Australia:
We are exempt from the requirement to hold an Australian financial services licence under the Corporations Act (as a result of the operation of ASIC Class Order 03/1099, as amended by the ASIC Corporations (Repeal and Transitional) Instrument 2016/396, and extended by the ASIC Corporations (Amendment) Instrument 2020/200) in respect of the financial services we provide to wholesale clients in Australia and are regulated by the Financial Conduct Authority under English laws which differ from Australian laws.
By entering this Website, you confirm that you are a wholesale investment professional, and meet the requirements to categorise yourself as such, according to the laws and regulations of Australia.
For investors in Switzerland:
If you are not able to access this Website according to the criteria in this paragraph, or you do not understand if you fulfil the relevant criteria, you must not agree to these Terms and Conditions. This Website is provided exclusively for use by, and for the information of, Professional investors (as defined in The Federal Financial Services Act).
By entering this Website, you confirm that you meet the entry criteria described above according to the laws and regulations of Switzerland.
Your account and password
If you choose, or you are provided with, a user identification code, password or any other piece of information as part of our security procedures, you must treat such information as confidential. You must not disclose it to any third party.
We have the right to disable any user identification code or password, whether chosen by you or allocated by us, at any time, if in our reasonable opinion you have failed to comply with any of the provisions of these Terms and Conditions.
If you know, or suspect, that anyone other than you knows your user identification code or password, you must promptly notify us.
You instruct us to accept as genuine and duly authorise any instruction placed using your identification code and password. Unless you advise us that your identification code and password have been compromised, any instruction using them will be deemed valid.
Intellectual property rights
The Royal London Mutual Insurance Society Limited and/or its subsidiary companies is/are the owner or the licensee of all intellectual property rights in this Website, and in the material published on it. Those works are protected by copyright laws and treaties around the world. All such rights are reserved.
You may print off one copy, and may download extracts, of any page(s) from this Website for your personal use and you may draw the attention of others within your organisation to content posted on this Website.
You must not modify the paper or digital copies of any materials you have printed off or downloaded in any way, and you must not use any illustrations, photographs, video or audio sequences or any graphics separately from any accompanying text.
The status (and that of any identified contributors) of The Royal London Mutual Insurance Society Limited and/or its subsidiary companies/another company in the Royal London Group as the authors of content on this Website must always be acknowledged.
If you print off, copy or download any part of this Website in breach of these Terms and Conditions, your right to use this Website will cease immediately and you must, at our option, return or destroy any copies of the materials you have made.
No reliance on information
The content on this Website is provided for general information only. It is not intended to amount to financial or other professional advice on which you should rely. You must obtain financial or other professional advice if you require it before taking, or refraining from, any action on the basis of the content on this Website.
Although we make reasonable efforts to update the information on this Website, we make no representations, warranties or guarantees, whether express or implied, that the content on this Website is accurate, complete or up-to-date.
Limitation of our liability
Nothing in these Terms and Conditions excludes or limits our liability for death or personal injury arising from our negligence, or our fraud or fraudulent misrepresentation, or any other liability that cannot be excluded or limited by applicable law.
To the fullest extent permitted by law, we exclude all conditions, warranties, representations, or other terms which may apply to this Website or any content on it, whether express or implied.
We will not be liable to any Website user for any loss or damage, whether in contract, tort (including negligence), breach of statutory duty, or otherwise, even if foreseeable, arising under or in connection with:
- use of, or inability to use, this Website; or
- use of or reliance on any content displayed on this Website.
If you are a business user, please note that in particular, we will not be liable for:
- loss of profits, sales, business, or revenue;
- business interruption;
- loss of anticipated savings;
- loss of business opportunity, goodwill or reputation; or
- any indirect or consequential loss or damage.
If you are a consumer user, please note that we only provide this Website for domestic and private use. You agree not to use this Website for any commercial or business purposes, and we have no liability to you for any loss of profit, loss of business, business interruption, or loss of business opportunity. We will not be liable for any loss or damage caused by a virus, distributed denial-of-service attack, or other technologically harmful material that may infect your computer equipment, computer programs, data or other proprietary material due to your use of this Website or to your downloading of any content on it, or on any website linked to it.
This Website may contain links to other websites. We assume no responsibility for the content of websites linked on this Website. Such links should not be interpreted as endorsement by us of those linked websites. We will not be liable for any loss or damage that may arise from your use of them.
Different limitations and exclusions of liability will apply to liability arising as a result of the supply of any products or services by us to you, which will be set out in the relevant product or service terms and conditions.
If, notwithstanding the other provisions of these Terms and Conditions, we are found to be liable to you for any damage or loss (including through negligence) which arises in any way out of, or is in any way connected with, your use of this Website, any content or service, our liability (save as prohibited by applicable law) shall in no event exceed the greater of the total of any amounts paid by you to us in relation to the part of this Website, content, product or service to which the claim relates in the six (6) months prior to the date of the initial claim and £100.00.
Viruses, hacking and other offences
You are responsible for configuring your information technology, computer programs and platform in order to access this Website. You should use your own virus protection software.
You must not misuse this Website by knowingly introducing viruses, trojans, worms, logic bombs or other material which is malicious or technologically harmful. You must not attempt to gain unauthorised access to this Website, the server on which this Website is stored, or any server, computer or database connected to this Website. You must not attack this Website via a denial-of-service attack or a distributed denial-of service attack. By breaching this provision, you would commit a criminal offence under the Computer Misuse Act 1990. We will report any such breach to the relevant law enforcement authorities and we will co-operate with those authorities by disclosing your identity to them. In the event of such a breach, your right to use this Website will cease immediately.
We will not be liable for any loss or damage caused by a distributed denial-of-service attack, viruses or other technologically harmful material that may infect your computer equipment, computer programs, data or other proprietary material due to your use of this Website or to your downloading of any material posted on it, or on any website linked to it.
Linking to this Website
You may link to our home page, provided you do so in a way that is fair and legal and does not damage our reputation or take advantage of it.
You must not establish a link in such a way as to suggest any form of association, approval or endorsement on our part where none exists.
You must not establish a link to this Website in any website that is not owned by you.
This Website must not be framed on any other website, nor may you create a link to any part of this Website other than the home page.
We reserve the right to withdraw linking permission without notice.
Third party links and resources in this Website
Where this Website contains links to other websites and resources provided by third parties, these links are provided for your information only.
We have no control over the contents of those websites or resources, and accept no responsibility for them or for any loss or damage that may arise from your use of them.
FTSE indices terms of use
We, and/or the Royal London Group, use indices of FTSE (“FTSE Indices”).The Funds have been developed solely by us. The Funds are not in any way connected to, or sponsored, endorsed, sold or promoted by, the London Stock Exchange Group plc and its group undertakings (collectively, the “LSE Group”). FTSE Russell is a trading name of certain of the LSE Group companies.
All rights in the FTSE Indices vest in the relevant LSE Group company which owns the FTSE Index. “FTSE®” is a trademark of the relevant LSE Group company and is used by any other LSE Group company under license.
The FTSE Index is calculated by, or on behalf of, FTSE International Limited or its affiliate, agent or partner. The LSE Group does not accept any liability whatsoever to any person arising out of (a) the use of, reliance on or any error in, the FTSE Index or (b) investment in, or operation of, the Funds. The LSE Group makes no claim, prediction, warranty or representation either as to the results to be obtained from the Funds, or the suitability of the FTSE Index for the purpose to which it is being put by Royal London Asset Management Limited.
JP Morgan indices terms of use
We, and/or the Royal London Group, use indices of JP Morgan (“JP Morgan Index”). Information has been obtained from sources believed to be reliable, but J.P. Morgan does not warrant its completeness or accuracy. The JP Morgan Index is used with permission. The JP Morgan Index may not be copied, used, or distributed without J.P. Morgan's prior written approval. Copyright 2018, J.P. Morgan Chase & Co. All rights reserved.
Barclays and Bloomberg indices terms of use
We, and/or the Royal London Group, use indices of Bloomberg and Barclays (“Bloomberg and Barclays Indices”). BLOOMBERG® is a trademark and service mark of Bloomberg Finance L.P. and its affiliates (collectively “Bloomberg”). BARCLAYS® is a trademark and service mark of Barclays Bank Plc (collectively with its affiliates, “Barclays”), used under license. Bloomberg or Bloomberg’s licensors, including Barclays, own all proprietary rights in the Bloomberg and Barclays Indices. Neither Bloomberg nor Barclays approves or endorses this material, or guarantees the accuracy or completeness of any information herein, or makes any warranty, express or implied, as to the results to be obtained therefrom and, to the maximum extent allowed by law, neither shall have any liability or responsibility for injury or damages arising in connection therewith.
MSCI indices terms of use
We, and/or the Royal London Group, use indices of MSCI (“MSCI Indices”). The Funds are not sponsored, endorsed, sold or promoted by MSCI INC. (“MSCI”), any of its affiliates, any of its information providers or any other third party involved in, or related to, compiling, computing or creating any MSCI Index (collectively, the “MSCI Parties”). The MSCI Indexes are the exclusive property of MSCI. MSCI and the MSCI Index names are service mark(s) of MSCI or its affiliates and have been licenced for use for certain purposes by the Royal London Mutual Insurance Society Limited and/or its subsidiary companies. None of the MSCI Parties makes any representation or warranty, express or implied, to the issuer or owners of the Funds or any other person or entity regarding the advisability of investing in funds generally, or in the Funds particularly, or the ability of any MSCI Index to track corresponding stock market performance. MSCI or its affiliates are the licensors of certain trademarks, service marks and trade names and of the MSCI Indexes which are determined, composed and calculated by MSCI without regard to the Funds or the issuer or owners of the Funds or any other person or entity.
None of the MSCI Parties has any obligation to take the needs of the issuer or owners of the Funds or any other person or entity into consideration in determining, composing or calculating the MSCI Indexes. None of the MSCI Parties is responsible for, or has participated in, the determination of the timing of, prices at, or quantities of the Funds to be issued, or in the determination or calculation of the equation by, or the consideration into, which Funds are redeemable. Further, none of the MSCI Parties has any obligation or liability to the issuer or owners of the Funds or any other person or entity in connection with the administration, marketing or offering of the Funds.
Although MSCI shall obtain information for inclusion in, or for use in the calculation of, the MSCI Indexes from sources that MSCI considers reliable, none of the MSCI Parties warrants or guarantees the originality, accuracy and/or the completeness of any MSCI Index or any data included therein. None of the MSCI Parties makes any warranty, express or implied, as to results to be obtained by the issuer of the Funds, the owners of the Fund, or any other person or entity, from the use of any MSCI Index or any data included therein. None of the MSCI Parties shall have any liability for any errors, omissions or interruptions of, or in connection with, any MSCI Index or any data included therein. Further, none of the MSCI Parties makes any express or implied warranties of any kind, and the MSCI Parties hereby expressly disclaim all warranties of merchantability and fitness for a particular purpose, with respect to each MSCI Index and any data included therein. Without limiting any of the foregoing, in no event shall any of the MSCI Parties have any liability for any direct, indirect, special, punitive, consequential or any other damages (including lost profits) even if notified of the possibility of such damages.
ICE indices terms of use
We, and/or the Royal London Group, use indices of ICE Data LLC (“ICE Data Indices”). ICE Data Indices are used with permission.
ICE Data LLC, its affiliates and their respective third-party suppliers, disclaim any and all warranties and representations, express and/or implied, including any warranties of merchantability or fitness for a particular purpose or use, including the ICE Data Indices, index data and any data included in, related to, or derived therefrom. Neither ICE Data LLC, its affiliates nor their respective third party suppliers shall be subject to any damages or liability with respect to the adequacy, accuracy, timeliness or completeness of the ICE Data Indices or the index data or any component thereof, and the ICE Data Indices and index data and all components thereof are provided on an “as is” basis and Royal London Mutual Insurance Society Limited’s use is at its own risk. ICE Data LLC, its affiliates and their respective third-party suppliers do not sponsor, endorse, or recommend Royal London Mutual Insurance Society Limited and/or its subsidiary companies, or any of its products or services.
Sterling Overnight Index Average (SONIA) terms of use
Source: BofE
The “SONIA” mark is used under licence from the Bank of England (the benchmark administrator of SONIA), and the use of such mark does not imply or express any approval or endorsement by the Bank of England. “Bank of England” and “SONIA” are registered trademarks of the Bank of England.
General
If we fail at any time to insist upon strict performance of any of your obligations under these Terms and Conditions, or if we fail to exercise any of the rights or remedies to which we are entitled under these Terms and Conditions, this shall not constitute a waiver of such rights or remedies and shall not relieve you from compliance with such obligations.
You agree that no joint venture, partnership, employment, or agency relationship exists between you and us as a result of these terms of use or use of this Website.
Nothing in these Terms and Conditions shall confer, or is intended to confer, on any person or corporation that is not party to these Terms and Conditions any benefit or the right to enforce any term of these Terms and Conditions.
The headings will not form part of these Terms and Conditions and will not affect their interpretation.
If any provision of these Terms and Conditions is held to be invalid or unenforceable, such provision shall be struck out and the remaining provisions shall remain in full force and effect.
Applicable law
If you are a consumer, please note that these Terms and Conditions, their subject matter and formation, are governed by English law. You and we both agree that the courts of England and Wales will have non-exclusive jurisdiction. However, if you are a resident of Northern Ireland you may also bring proceedings in Northern Ireland, and if you are resident of Scotland, you may also bring proceedings in Scotland.
If you are a business, these Terms and Conditions, their subject matter and formation (and any non-contractual disputes or claims), are governed by English law. We both agree to the exclusive jurisdiction of the courts of England and Wales.


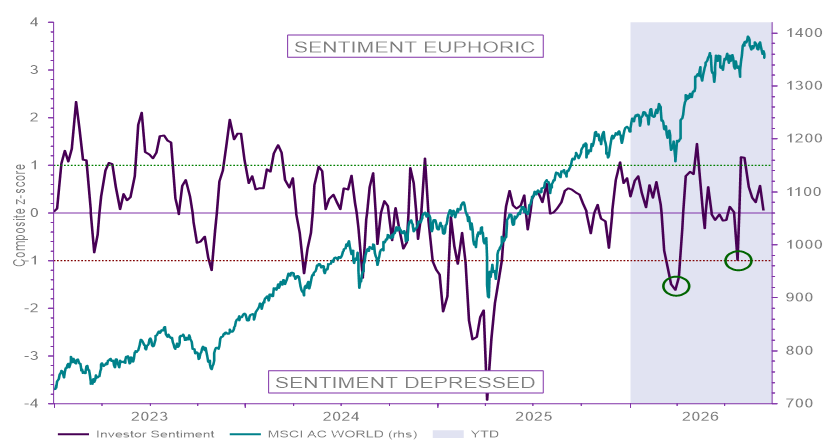 Source: RLAM, LSEG DataStream as at 11 September 2026.
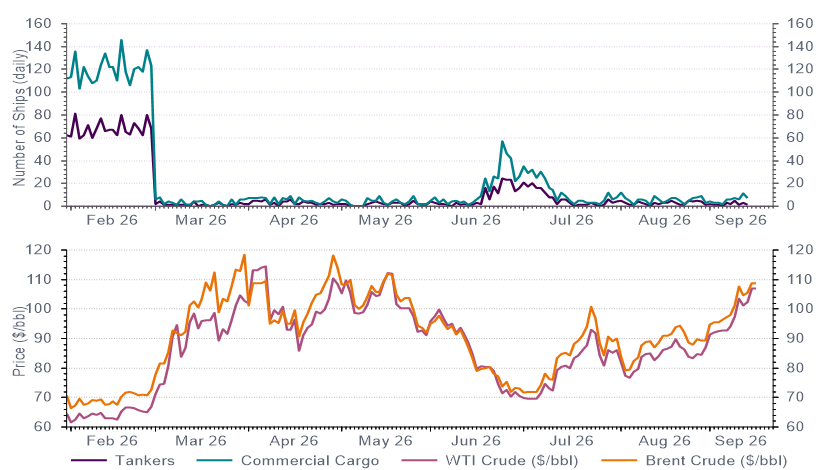 Source: RLAM, Bloomberg, LSEG DataStream as at 14 September 2026.